If an AI Agent Signs a Contract, Who Is Legally Responsible?
Read More
Buying a Company in India: A Buyer's Legal Due Diligence Checklist Before Signing a Share Purchase Agreement
By the SolvLegal Team
Published on: Oct. 4, 2026, 8:03 p.m.
A company can look healthy on paper and still carry problems the accounts do not show. An old tax notice, a licence held in the founder's name, a customer contract that ends the day ownership changes. None of this appears in a pitch deck.
That is the core issue when you buy shares in an Indian private company. You are not picking out assets. You are buying the company itself, with its history, its contracts and its liabilities. Ownership of the entity changes. What sits inside it generally stays where it was.
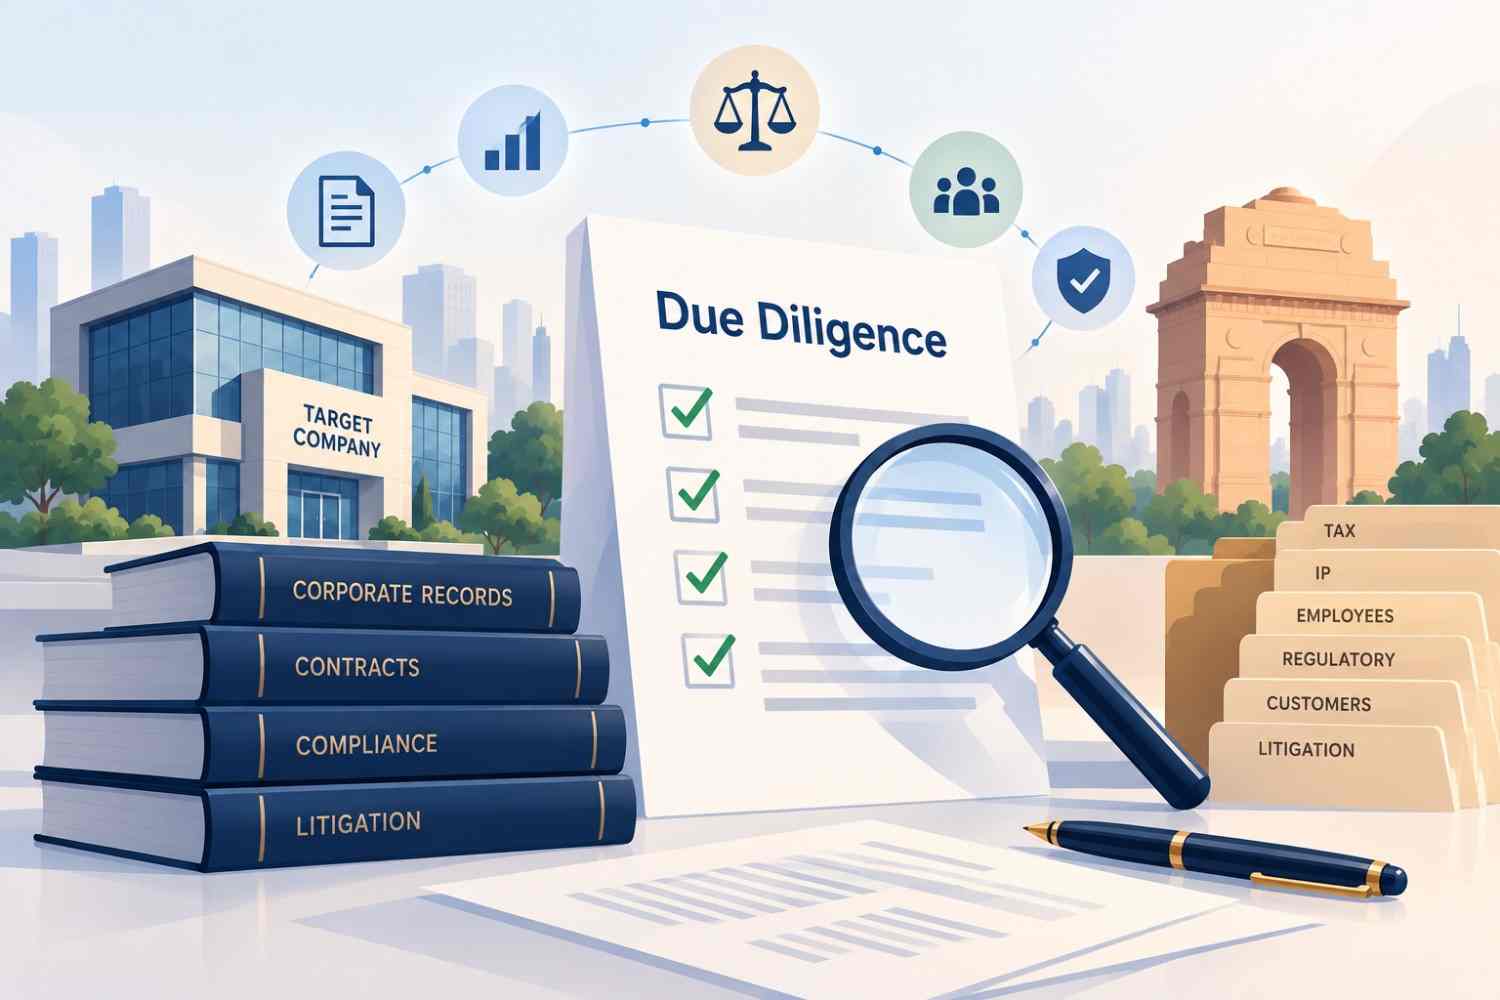
Legal due diligence is how a buyer finds out what is inside before accepting the risk allocation in the Share Purchase Agreement (SPA). One question runs through the whole process. What is the buyer actually acquiring, what liabilities remain inside the target, and what contractual protection is needed if a risk cannot be removed before closing?
This guide covers the checks, the law behind them and the way findings feed into the SPA. It is general information, not advice on any specific deal.
Share purchase or asset purchase: which structure should a buyer choose?
Structure comes first because it decides what you inherit.
In a share purchase, you buy shares from the existing shareholders. The company carries on as before, with the same contracts, licences, employees and liabilities. In an asset or business purchase, you choose what to take, and each asset or contract may need its own transfer step.
Neither route wins every time. A share deal keeps the business running without re-papering every contract. It also brings the target's history along. A business transfer allows more selection, but it may need more consents and more paperwork.

Tax and stamp duty treatment also differ between structures, so tax advice should come before the structure is fixed. This article focuses on share purchases.
What corporate and share capital records should a buyer check?
Start with the basics. Does the company exist in good standing? Do the sellers actually own the shares they are selling?
Ask for the certificate of incorporation, the memorandum and articles of association, board and shareholder resolutions, share certificates and the statutory registers required under the Companies Act, 2013. Then reconcile them with the public record on the MCA portal. Authorised, issued and paid-up capital should match across registers, filings and the cap table.
Look hard at history. Was each allotment properly approved? Were existing shareholders' rights respected? Were past transfers made on valid, stamped instruments? A defect in an old allotment can cloud title to the shares you are about to buy.
Read the articles and any shareholders' agreement together. Private companies usually restrict share transfers in their articles. Shareholder agreements often add pre-emption, tag-along, drag-along and veto rights. Any of these can block or reshape your deal.
Two more checks matter. The first is beneficial ownership. The Act requires declarations of beneficial interest and reporting of significant beneficial owners, so the name on the register may not be the person who really holds the shares. The second is charges. Registered charges over the company's assets appear on the MCA record, and they should match the loan documents you are shown.
Finally, look at related-party dealings, including loans to directors, and check that annual filings are up to date. Confirm the current text of the Act and Rules before relying on any section.
Who owns the brand, software and data behind the business?
A buyer pays for what the business earns. That value often rests on assets the target may not own.
Check trademarks first: registered owner, pending applications, renewals and disputes. Then look at software and source code, domain names, websites, databases, social media handles, app store accounts and cloud accounts. Ask who holds the login credentials, and whose name and email sit behind them.
Ownership of created work is the common trouble spot. Under Section 17 of the Copyright Act, 1957, the author is generally the first owner of a work, but the section sets out exceptions. For a work made in the course of employment under a contract of service, the employer is generally the first owner unless there is an agreement to the contrary. Other exceptions cover certain commissioned works, such as photographs, portraits and cinematograph films made for valuable consideration, and works made by or under the direction of the Government. Who owns a particular work therefore depends on its type, the circumstances in which it was created and the terms agreed. Where a freelancer, agency or contractor created software, content or design, the rights may not sit with the target unless they were assigned in writing. Verify written IP assignments from founders, employees, consultants, agencies and other creators, and check confidentiality terms.
The problem sharpens when a founder, a group company or a contractor holds the essential IP instead of the target. The buyer then acquires a company that depends on an asset it does not own. The usual fixes are a written assignment before closing, a proper licence, or a price change.
For technology and e-commerce targets, give this section extra time. Review open source use and third-party licences too, since some restrict use after a change of control.
Which contracts can end or change when ownership changes?
Revenue in the accounts says little about whether it will continue. A customer that brings in a large share of sales may be able to terminate once the target has a new owner.
In a share deal, contracts stay with the company, so a plain assignment clause may not be triggered. Change-of-control clauses are different. They are often written to catch a share sale.
Read customer, supplier, distributor, cloud and software agreements, licences, loan documents and leases. Look for termination rights, exclusivity, minimum commitments, unusual indemnities, renewal terms and consent requirements. Lenders and landlords deserve special attention because their consent rights are common.
Where a key consent is needed, the SPA can make it a condition to closing. Where it cannot be obtained, the price may need to reflect the risk.
How do tax and financial liabilities affect a share purchase?
Legal due diligence and financial or tax due diligence are different jobs. Lawyers review notices, orders, filings and contracts. Accountants test the numbers. Tax specialists advise on exposure. A legal review should not be presented as an accounting or tax opinion.
Still, the legal team has to ask the right questions. Are there pending assessments, demands or appeals on income tax, GST or TDS? Have provident fund and other payroll dues been paid? Are there notices the financial statements do not mention?
Timing adds a wrinkle. The Income tax Act, 2025 came into force on 1 April 2026, replacing the Income tax Act, 1961. The repeal does not disturb anything relating to tax years before that date. A target may therefore carry historic exposure under the old Act and current compliance under the new one.
What the review finds can change the deal. A known exposure may become a condition to closing, a specific indemnity, an escrow or a price reduction. Tax advisers should confirm the numbers before those choices are made.
What should a buyer check about employees, founders and key people?
Start with the paperwork. Review employment and consultancy agreements, pay structures, statutory dues, confidentiality terms and IP assignments. Check ESOP plans and outstanding grants too, because they affect the cap table.
Labour law has also moved. Four labour codes were brought into force on 21 November 2025, and central rules under them were notified in May 2026, with state rules following separately. Pay structures and policies should be checked against the current position. Then look at dependency. In many private companies, the founder holds the client relationships and sometimes the IP. If that person leaves after closing, the business may lose much of its value.
Contract terms only go so far here. Post-employment non-compete promises are generally hard to enforce in India because of Section 27 of the Indian Contract Act, 1872. The section does make an exception for a person who sells goodwill, so a carefully drafted covenant in the SPA may carry more weight, within reasonable limits. Retention often works better through deferred payments, vesting and transition undertakings.
In a share purchase, the employing entity generally stays the same. In a business transfer, the employee consequences can differ, so they should not be assumed.
What litigation and regulatory issues should a buyer look for?
Ask for a list of pending and threatened disputes, notices, investigations and orders. Then check it yourself against court, tribunal and MCA records. Include consumer, arbitration, labour and tax matters. Contingent liabilities noted in the financial statements can point to disputes the sellers forgot to mention.
Next, confirm the target holds the licences and registrations its business needs, and that they are current.
Sector matters here. Fintech, healthcare, food, telecom and education businesses need extra regulatory analysis, and some approvals are tied to ownership or control. For those targets, a general checklist is only a starting point.
What data protection checks apply when buying a digital business?
Customer databases often carry a large part of an e-commerce or Technology Company’s value. That value depends on how the data was collected and how it is used.
Review what personal data the target holds about customers and employees, what its privacy notices promise, how consent was obtained and which vendors process the data. Ask about past security incidents and how they were handled. Read website and app terms, and check consumer-facing practices and marketing lists.
The legal framework is still phasing in. The Digital Personal Data Protection Act, 2023 is being commenced in stages. The Rules were notified in November 2025 and take effect in three phases, with the main obligations for businesses scheduled for 13 May 2027. Until the newer provisions take over, the older framework under the Information Technology Act, 2000 remains relevant. Do not assume every provision is operational. Confirm the position on the date of the deal, using MeitY and Gazette notifications.
A buyer should also price in the cost of bringing the target into line. Warranties on data handling, and disclosure of past incidents, help allocate that risk.
Does a foreign buyer need extra approvals to buy an Indian company?
Not every deal raises foreign investment questions. If the buyer and sellers are all resident in India, FEMA analysis may not arise. If either side is a non-resident, it does.
The buyer then looks at the Foreign Exchange Management Act, 1999, the Non-Debt Instruments Rules, 2019 and the FDI policy issued by DPIIT. The questions include whether the sector allows foreign investment, whether the automatic or government route applies, what sectoral caps and conditions exist, how the price must be set, how payment can move and what must be reported to the RBI. Deferred payment and escrow arrangements also face specific conditions in cross-border transfers, so an earn-out for a foreign buyer needs its own check.
Investors linked to countries sharing a land border with India face a separate regime, and it was revised in 2026. Under Press Note 2 (2026 Series), dated 15 March 2026, such an entity or citizen, or an investor whose beneficial owner is a citizen of such a country, can still invest only through the Government route. A later change in beneficial ownership that brings an investment within that restriction also needs prior approval. What changed is the test for beneficial ownership. It now follows the Prevention of Money-laundering Act, 2002 and Rule 9(3) of the PML Rules, applied through the investor entity. Where an investment has some land-border ownership but does not need prior approval, it must still be reported in the format DPIIT prescribes, in addition to sectoral caps and entry-route conditions. The Foreign Exchange Management (Non-debt Instruments) (Amendment) Rules, 2026, notified in May 2026, give effect to these changes. Whether approval, reporting or neither applies depends on the ownership chain, so check the current RBI and DPIIT position for the specific deal before signing.
Does the acquisition need Competition Commission of India approval?
Not every acquisition does. A deal needs CCI clearance only if it is a "combination" under Section 5 of the Competition Act, 2002. That means an acquisition of shares, voting rights or control that crosses the prescribed asset or turnover thresholds, or the deal value test.
The monetary limits can be revised by the government, so they should be checked on the date of the deal. The small-target exemption now rests on the Competition (Minimum Value of Assets or Turnover) Rules, 2024 (G.S.R. 547(E)), in force since 10 September 2024. Under these Rules, a target with assets in India of not more than ₹450 crore, or turnover in India of not more than ₹1,250 crore, falls outside the notification requirement. The two tests are alternatives, so meeting either one is enough. The Rules codified the same figures that a March 2024 notification (S.O. 1131(E)) had set for two years, and the Rules themselves carry no expiry date. The exemption does not help where the deal-value test, explained below, applies.
A deal value test also applies since the 2023 amendment. Approval is needed for a deal worth more than ₹2,000 crore, counting deferred consideration, where the target has substantial business operations in India, even if the target would otherwise be exempt.
If notification is required, the parties cannot complete the deal before approval. Closing early risks a gun-jumping penalty. The SPA should therefore make CCI clearance a condition to closing, and the timetable should allow for the review period. Until clearance arrives, the buyer should not take control of the target or receive commercially sensitive information beyond what the process permits.
How do you turn due diligence findings into SPA protection?
This is where diligence earns its cost. A finding that stays in a report protects nobody. It needs a home in the contract.
The right tool depends on the risk. Can it be fixed before closing? Can it be measured? Who can pay if a claim arises? How much bargaining power does each side have? The table shows common pairings.

Price and protection are linked. Sometimes it is simpler to cut the price than to negotiate a detailed indemnity. Collection matters too. An indemnity from an individual seller is only as good as that person's ability to pay. That is why escrow and holdback arrangements are common where the exposure is real.
None of these tools removes risk completely. They allocate it.
What is the difference between warranties and indemnities in an SPA?
They are often mentioned together, but they do different jobs.
A warranty is a statement of fact about the company. For example, that its accounts are accurate, that it owns its IP or that it has no undisclosed litigation. If the statement is untrue, the buyer may claim compensation. Warranties protect against risks nobody has spotted yet.
An indemnity is a promise to compensate the buyer for a defined loss. It usually covers a known risk, such as a pending tax demand, and it does not depend on any statement being false.
The difference matters because of disclosure. Sellers typically disclose exceptions against the warranties, and a disclosed matter can weaken a warranty claim. A risk the buyer already knows about needs its own specific indemnity.
Several terms decide how much protection the buyer really has. Knowledge qualifiers limit a warranty to what the seller knew, so the definition of knowledge matters. A cap limits total liability. A basket sets a minimum before claims count, and a de minimis amount excludes small claims. Survival periods fix how long claims can be brought. Procedural clauses set out how claims are notified and defended.
There is no single market formulation for every Indian deal. Terms shift with sector, deal size and bargaining position.
What happens between signing and closing an Indian share deal?
Signing fixes the terms. Closing is when ownership passes. In between, the parties work through conditions precedent, the steps that must be completed before the deal can close.
Typical conditions include corporate approvals from the target and the sellers, waivers of pre-emption or transfer restrictions, third-party consents, regulatory clearances and release of security. They can also include any restructuring or carve-out the buyer requires.
At closing, the parties exchange documents and money. That covers signed transaction documents, payment through banking channels, the share transfer, changes to the board, handover of records and control of accounts and digital assets.
Transfer mechanics depend on the target. Rule 9B of the Companies (Prospectus and Allotment of Securities) Rules, 2014 requires a private company that is not a small company to issue securities only in demat form and to facilitate demat of existing securities. A small company sits outside that rule, and its transfers may use a physical, duly stamped instrument. Stamp duty depends on the instrument and the applicable law, so no single rate should be assumed.
After closing, the work continues. Update the registers, make the required filings with the Registrar, complete any FEMA reporting and record the satisfaction of charges.
How do deferred consideration and earn-outs work?
Not every price is paid at closing. Part of it may be deferred, held in escrow or linked to future performance. Buyers use these structures to bridge a valuation gap, keep founders involved and hold money back against risks that appear later.
An earn-out lives or dies on its drafting. Metrics should be objective, such as revenue or a defined profit measure. The accounting policies used to calculate them should be fixed in advance. The agreement should say how results are attributed if the business is merged into the buyer's operations.
Then comes the tension. The buyer wants freedom to run the business. The seller wants protection against decisions that push the numbers down. Both concerns need terms. Information and audit rights, set-off against indemnity claims, caps and floors, and a dispute mechanism for calculations complete the design. The agreement should also say what happens if the business model changes after closing.
Two flags apply. In a cross-border deal, FEMA conditions can apply to deferred payments. And, as noted above, deferred consideration can count toward the CCI deal-value test.
Practical buyer's checklist before signing the SPA
- Confirm the target, the shares being sold and the deal structure.
- Verify the sellers' title and the company's corporate and share capital records.
- Identify who owns the key IP, domains, data and accounts.
- Review material contracts for change-of-control, termination and consent terms.
- Complete legal, financial and tax diligence, with specialists handling tax.
- Investigate litigation, notices, licences and sector approvals.
- Resolve FEMA, FDI and CCI questions where they apply.
- Map every consent and approval needed before closing.
- Convert findings into conditions, warranties, indemnities, price terms or covenants.
- Align closing deliverables and coordinate legal, tax and financial advisers.
Why legal due diligence is more than a checklist
A checklist gets the documents into the room. The value comes from what you do with them. Some risks can be corrected before completion. Some should change the commercial deal. Others need to be allocated through the SPA and related documents. In cross-border acquisitions, the legal work should also be coordinated with tax, financial and foreign-investment advice.
Transaction specific legal, tax and regulatory analysis depends on the target, the parties, the sector and the structure. This article is general information and not legal advice.
Frequently asked questions
1. What legal due diligence should a buyer conduct before buying a private company in India?
Review corporate records and share capital, IP ownership, key contracts, tax and statutory compliance, employment, litigation, licences and data practices. Add FEMA and CCI checks where they apply, and sector rules for regulated businesses.
2. Does buying shares mean the buyer takes over the company's old liabilities?
Generally, yes. The company remains the same legal entity, so its existing liabilities generally stay inside it. The buyer's protection comes from diligence, price and SPA terms.
3. What is the difference between a share purchase and an asset or business purchase in India?
In a share purchase, the buyer acquires shares and the company continues as it is. In an asset or business purchase, the buyer takes selected assets and contracts, which may need individual transfer steps and consents. Tax and stamp duty treatment can differ.
4. What should a buyer check before signing an SPA?
Title to the shares, ownership of key IP, change-of-control and consent requirements, tax and litigation exposure, and regulatory approvals. Also check that the warranties, indemnities and conditions match what diligence found.
5. How do warranties and indemnities protect a buyer?
Warranties give the buyer a claim if statements about the company prove untrue. Indemnities cover defined losses, often known risks. Caps, baskets, time limits and disclosures shape how much protection results.
6. What happens if due diligence identifies a tax or litigation risk?
The buyer can ask for remediation before closing, negotiate a specific indemnity, escrow or holdback, reduce the price, or walk away. The choice depends on the size of the risk, how certain it is and the bargaining position.
7. What additional rules apply when a foreign buyer acquires an Indian company?
FEMA, the NDI Rules and the FDI policy apply, along with sectoral conditions, pricing rules and reporting duties. Investors linked to land-border countries face a separate regime. Check current RBI and DPIIT rules.
8. Does every acquisition in India require CCI approval?
No. Only combinations that meet the asset, turnover or deal-value tests, and that no exemption covers, need prior approval. Check the current thresholds and exemptions on the date of the deal.
9. What should be checked when acquiring an e-commerce or technology company?
IP ownership, source code and account control, open-source licences, customer data and consent practices, security incidents, consumer-facing compliance and key vendor contracts.
10. Can part of the purchase price be deferred or linked to future performance?
Yes. Deferred consideration, escrow and earn-outs are common. They need clear metrics, accounting rules, information rights, set-off and dispute terms. FEMA and competition rules may also apply.
Related Articles
ABOUT AUTHOR
This blog was written by Rakshika Bajpai, a corporate lawyer specialising in IPR, contract drafting, and compliance advisory. She is a technology-driven legal professional focusing on corporate compliance and data-privacy frameworks at SolvLegal. Her work spans IT law and cross-border regulatory matters, and she supports businesses in protecting their innovations and strengthening their legal and compliance structures.
Disclaimer
This article is intended solely for general informational and educational purposes. It does not constitute legal, tax or financial advice, advertising, or solicitation. Legal, tax and regulatory requirements in an acquisition depend on the target company, the parties, the sector, the deal structure and the governing documents. Thresholds, exemptions, filing requirements and commencement dates discussed here may change, and the position should be verified against current primary sources at the time of any transaction. Independent professional advice should be obtained before signing a share purchase agreement or relying on any due diligence findings.

Related Articles
Leave a Comment